Property Tax Measures Win in Five States, Fail in Two
Florida’s Amendment 3 won 62% of the vote, clearing the 60% threshold required for constitutional changes. It will increase the homestead exemption for nonschool property taxes to $150,000 in 2027 and $250,000 in 2028, with future adjustments for inflation. The measure also lowers the annual assessment increase limit for nonprimary residences from 10% to 5%. A state economic panel estimates the exemption will reduce annual property-tax revenue by $12 billion once fully implemented in 2028.
North Carolina voters approved a constitutional amendment requiring lawmakers to limit increases in the total property-tax collections of local governments. Tennessee voters added a constitutional ban on state-level property taxes, which the state had already stopped levying in 1949; local governments can continue to collect them.
Louisiana voters approved four changes expanding exemptions for seniors and surviving spouses of disabled veterans, and broadening access to assessment freezes. They rejected proposals concerning tax breaks for rehabilitated properties and local governments’ authority to raise rates without another voter vote. Georgia approved expanded preferential tax treatment for agricultural and timberland properties.
Wyoming voters rejected a proposal to exempt half the value of a primary residence. Oklahoma voters also turned down a measure that would have reduced annual assessment caps for homes and other properties. The defeats underscore concerns that limiting property-tax revenue could shift costs to other taxpayers or lead to cuts in public spending.
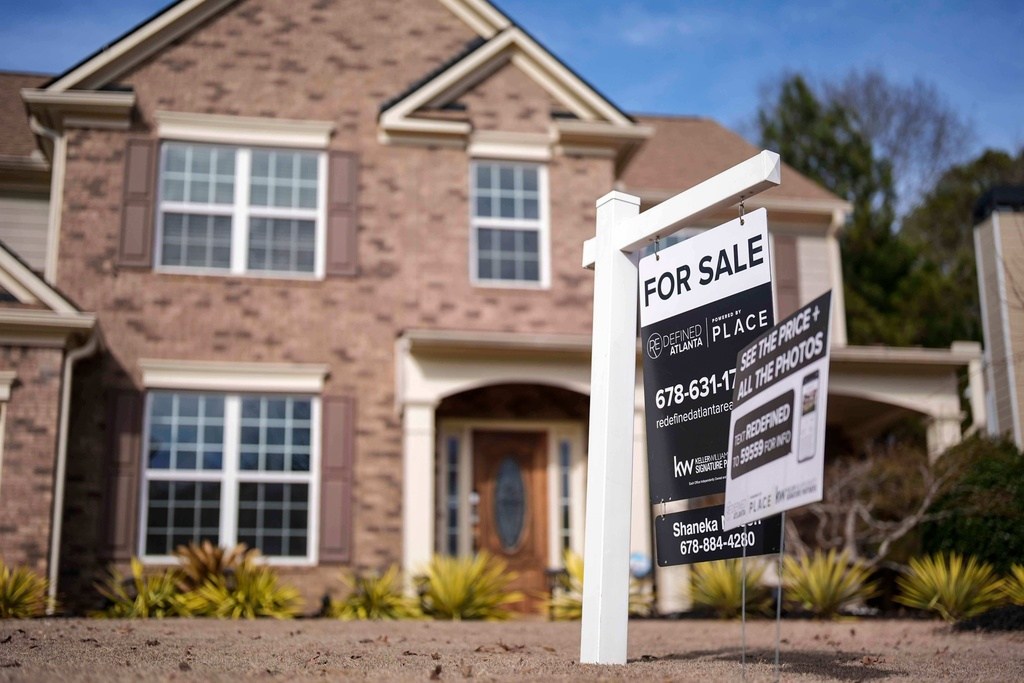
Supporters of tax relief argue that homeowners need help as home values and tax bills rise. Critics warn that local governments could make up lost revenue through other taxes, state or federal transfers, or borrowing, rather than reduce spending. Property taxes account for about 44% of revenue local governments raise themselves, making substantial cuts a significant budget issue.
Property Tax Cuts Win, but Local Services Face Revenue Risk
Florida voters approved a large property-tax break even as its projected cost to local revenues reaches $12 billion a year by 2028. Amendment 3 passed with 62% support and will raise the homestead exemption to $250,000 for nonschool property taxes. It also reduces the assessment-growth cap for nonprimary homes.
The votes came amid rising home values and tax bills, pressures that can burden homeowners. But the revenue reductions carry consequences beyond individual tax bills. Property taxes provide about 44% of the revenue local governments raise themselves, and significant reductions may mean less funding for services or a shift to sales and other taxes, transfers, or debt.
North Carolina voters approved a requirement for lawmakers to limit local governments’ total property-tax collections. Tennessee enshrined a ban on state-level property taxes, though local levies remain permitted. Louisiana approved four targeted expansions of exemptions and assessment freezes, while Georgia broadened favorable treatment for agricultural and timberland properties.
Wyoming and Oklahoma voters rejected proposed tax limits. Those defeats reflect the unresolved question behind the revolt: how to offer homeowners relief without moving the bill elsewhere or cutting public spending. Tax reductions alone do not determine which local responsibilities or services should shrink, while the revenue at stake is substantial.
Voters Demand Property Tax Relief Across Five States
Homeowners’ demand for relief from rising property taxes produced clear victories in five states. Florida’s Amendment 3 passed with 62% of the vote, expanding the homestead exemption for nonschool property taxes to $250,000 by 2028 and lowering the annual assessment cap for nonprimary residences. North Carolina voters also directed lawmakers to limit growth in local governments’ total collections.
The results show voters are willing to put limits on property taxation as home values and tax bills climb. Tennessee voters placed the state’s existing ban on state-level property taxes in its constitution, while keeping local governments’ authority to levy them. Louisiana approved four targeted changes for seniors, surviving spouses of disabled veterans and assessment-freeze eligibility. Georgia expanded preferential treatment for agricultural and timberland properties.
The proposals did not all prevail: Wyoming rejected a measure to exempt half of primary-home value, and Oklahoma turned down lower assessment caps. But those losses do not erase the broader push for tax relief. Florida’s measure is projected to reduce annual property-tax revenue by $12 billion when fully in place.
The central dispute is whether governments should respond to tax limits by trimming spending or replacing revenue through other taxes, transfers or borrowing. Local property taxes account for about 44% of the revenue governments raise themselves. The ballot results put pressure on officials to address taxpayers’ bills while deciding how to manage that revenue constraint.
Reported by The Washington Examiner, Reason.